Key Takeaways
- When consumers are price impacted, they may absorb higher prices, trade down, or walk away entirely. Each response points to different risks and opportunities for a brand.
- One QSR brand used historical category price response data alongside brand data to identify a stronger window for a price adjustment.
- Brand Price Response Indicators apply the same framework below the category level. This enables teams to compare their own pricing headroom against competitors and category benchmarks.
Tracking Lost Demand That Sales Data Misses
When inflation surged in 2022, clients were asking the same question: How were higher prices affecting their category, and how were consumers responding? Sales data answers only part of that question. It shows what consumers bought, but not which purchases they considered and abandoned, or why. Morning Consult’s economics team built the Price Response Indicators (PRI) to fill that gap.
The PRI framework follows a simple three-question sequence, fielded monthly across 21 categories. It begins with considerers, defined as consumers who purchased or considered purchasing in a category that month. This group represents the total pool of potential demand. Consumers who completed a purchase are then asked whether they paid more than expected (price absorbed), switched to a cheaper alternative (traded down), or paid what they expected (normal buying experience). Consumers who didn't purchase are asked why, and those who cite price as the reason for non-purchase are classified as price sensitive. The total group who experienced any price friction, including price absorbers, consumers trading down, and price-sensitive consumers make up the price-impacted share.
Together, relative balances and shifts over time in price response behaviors show how consumers are responding to market prices. Comparing these patterns across categories can help clients determine whether conditions are more or less favorable for a price adjustment.
Context Determines Whether a Response Is a Risk or an Opportunity
How to interpret each indicator depends on a brand’s position in its category and how that category fits into consumers’ overall spending.
- Price absorbers: A higher share can signal pricing headroom because these consumers noticed the higher price and bought anyway. But the higher price still registered, making price absorption a sign of pressure as well. For premium brands performing well, price absorbers may make up a large share of completed purchases. For value brands, rising price absorption may signal greater risk of losing customers to a cheaper competitor.
- Trading down: This indicator can cut both ways. Trading down preserves demand that might otherwise disappear, benefiting the brand that offers the cheaper option. But it also means a higher-priced sale was considered and ultimately lost, leaving some potential outlay unspent.
- Price sensitive: This is the clearest negative signal. These consumers considered a purchase but walked away because the price exceeded what they were willing to pay. Premium brands may naturally have a higher price-sensitive share when exclusivity is part of their positioning. In that case, the balance between price-sensitive consumers and price absorbers matters most.
How a Quick-Service Restaurant Used PRI to Time a Price Adjustment
Brands may have only a few opportunities to adjust prices each year, making timing an important part of the decision. Morning Consult’s macro, category, and brand data can help teams compare possible windows and understand the demand risks in each.
For example, a premium quick-service chain was considering two potential price-change windows: January and June. The team expected January to be riskier, assuming consumers would be more price sensitive as they recovered from holiday spending. Instead of relying on that assumption, it used Morning Consult PRI and brand data to compare the demand risk in each window. The analysis followed three steps:
- Compare the potential windows: The team reviewed category PRI across several years to see how consumer demand and price responses differed between the proposed months.
- Identify the relevant price responses: It focused on the behaviors most relevant to the brand’s position because the same response can have different implications. For instance, trading down can hurt a higher-priced brand but benefit a value brand.
- Validate the pattern with brand data: The team checked whether the category pattern also appeared in the brand’s own performance metrics.
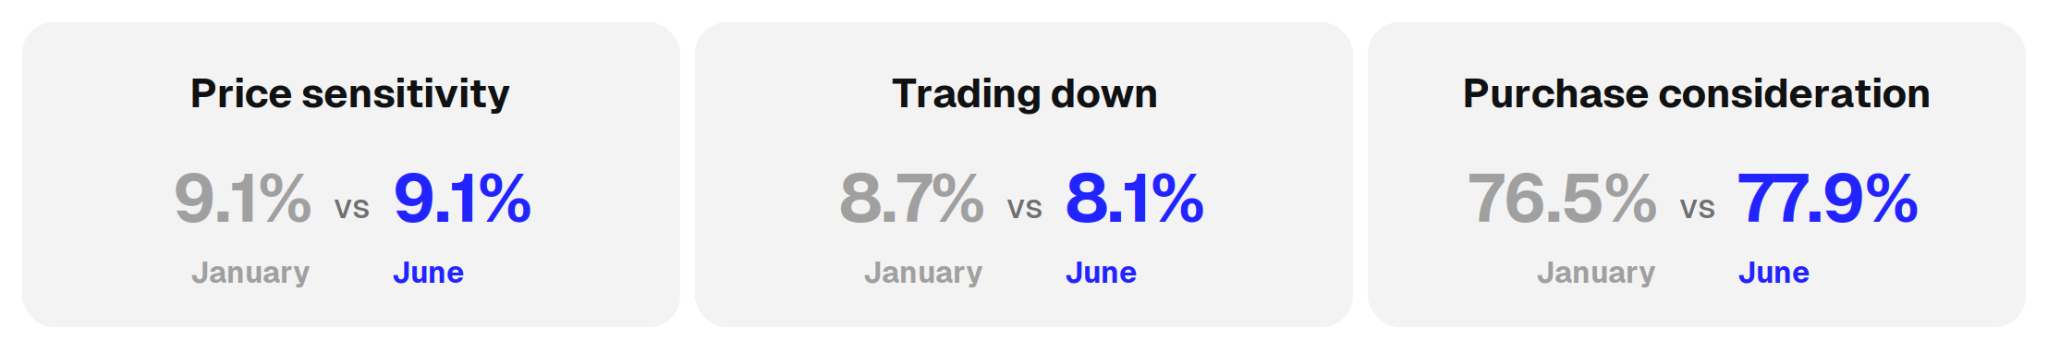
At the category level, restaurant price sensitivity was the same in January and June at 9.1%, so walk-away risk did not distinguish the two windows. Trading down was higher in January, at 8.7% compared with 8.1% in June. Purchase consideration was also lower in January, at 76.5% compared with 77.9%, a pattern that held across all three years analyzed. This revealed that fewer consumers were considering restaurant purchases at all in January, and those who did were more likely to choose a cheaper option.
But the category data alone could not show whether trading-down behavior helped or hurt this particular brand. A premium-positioned QSR can sit on either side of the decision: It may gain consumers trading down from a more expensive dining option or lose consumers to a cheaper QSR. The team therefore checked the category pattern against Morning Consult brand data.
The result: The brand-level data showed that weekly-or-more visitation was higher in June than in January in each year analyzed. This confirmed June as the stronger pricing window and gave the team a clear, data-backed basis for its decision. Rather than relying on a broad assumption about post-holiday financial pressure, the team could see what actually made January less favorable: lower consideration and greater substitution, not greater walk-away risk.
Go Beyond Category Averages with Brand PRI
Price Response Indicators in Morning Consult Intelligence cover 21 categories representing most of the consumer wallet, but consumer price responses can vary considerably within each category. Restaurant trends may look different across QSR and fine dining, just as responses within telecom may differ between streaming and wireless services. Clients have requested more brand-specific detail to make PRI insights more actionable.
Morning Consult’s Brand PRI, introduced this year, applies the framework to specific brands and their competitors, as well as more granular subcategories. This custom survey can be tailored to the level of detail a client needs, while category-level PRI provides historical and market context.
Together, category and Brand PRI give teams the context to understand the market and the precision to decide what it means for their specific brand.
Ready to get started? Request a demo
Consumers Say Gas Prices Have Gone Up, and Blame Trump
Consumer Sentiment Falls As Gas Prices Spike — But Expectations Remain Anchored